NRI-first · family-run insurance practice

Two generations of the same promise.

My father took a VRS (Voluntary Retirement Scheme) from The New India Assurance Co. and started this practice in 2004. I still run it the way he did — one family at a time, and mostly for people someone we know sent our way.

Featured NRI Term Plans — buy from abroad, at Indian rates ↗

A $100 Amazon gift card on joining the JMCC family.

Sign up, sit down with us for your complimentary planning session, and we send you a $100 Amazon gift card as a welcome. One per household. No purchase needed.

Two minutes · no cost · no obligation to buy

2Generations at the desk
3Insurers we place with
$100Amazon card on joining

The desk

Licensed agents, all reachable directly.

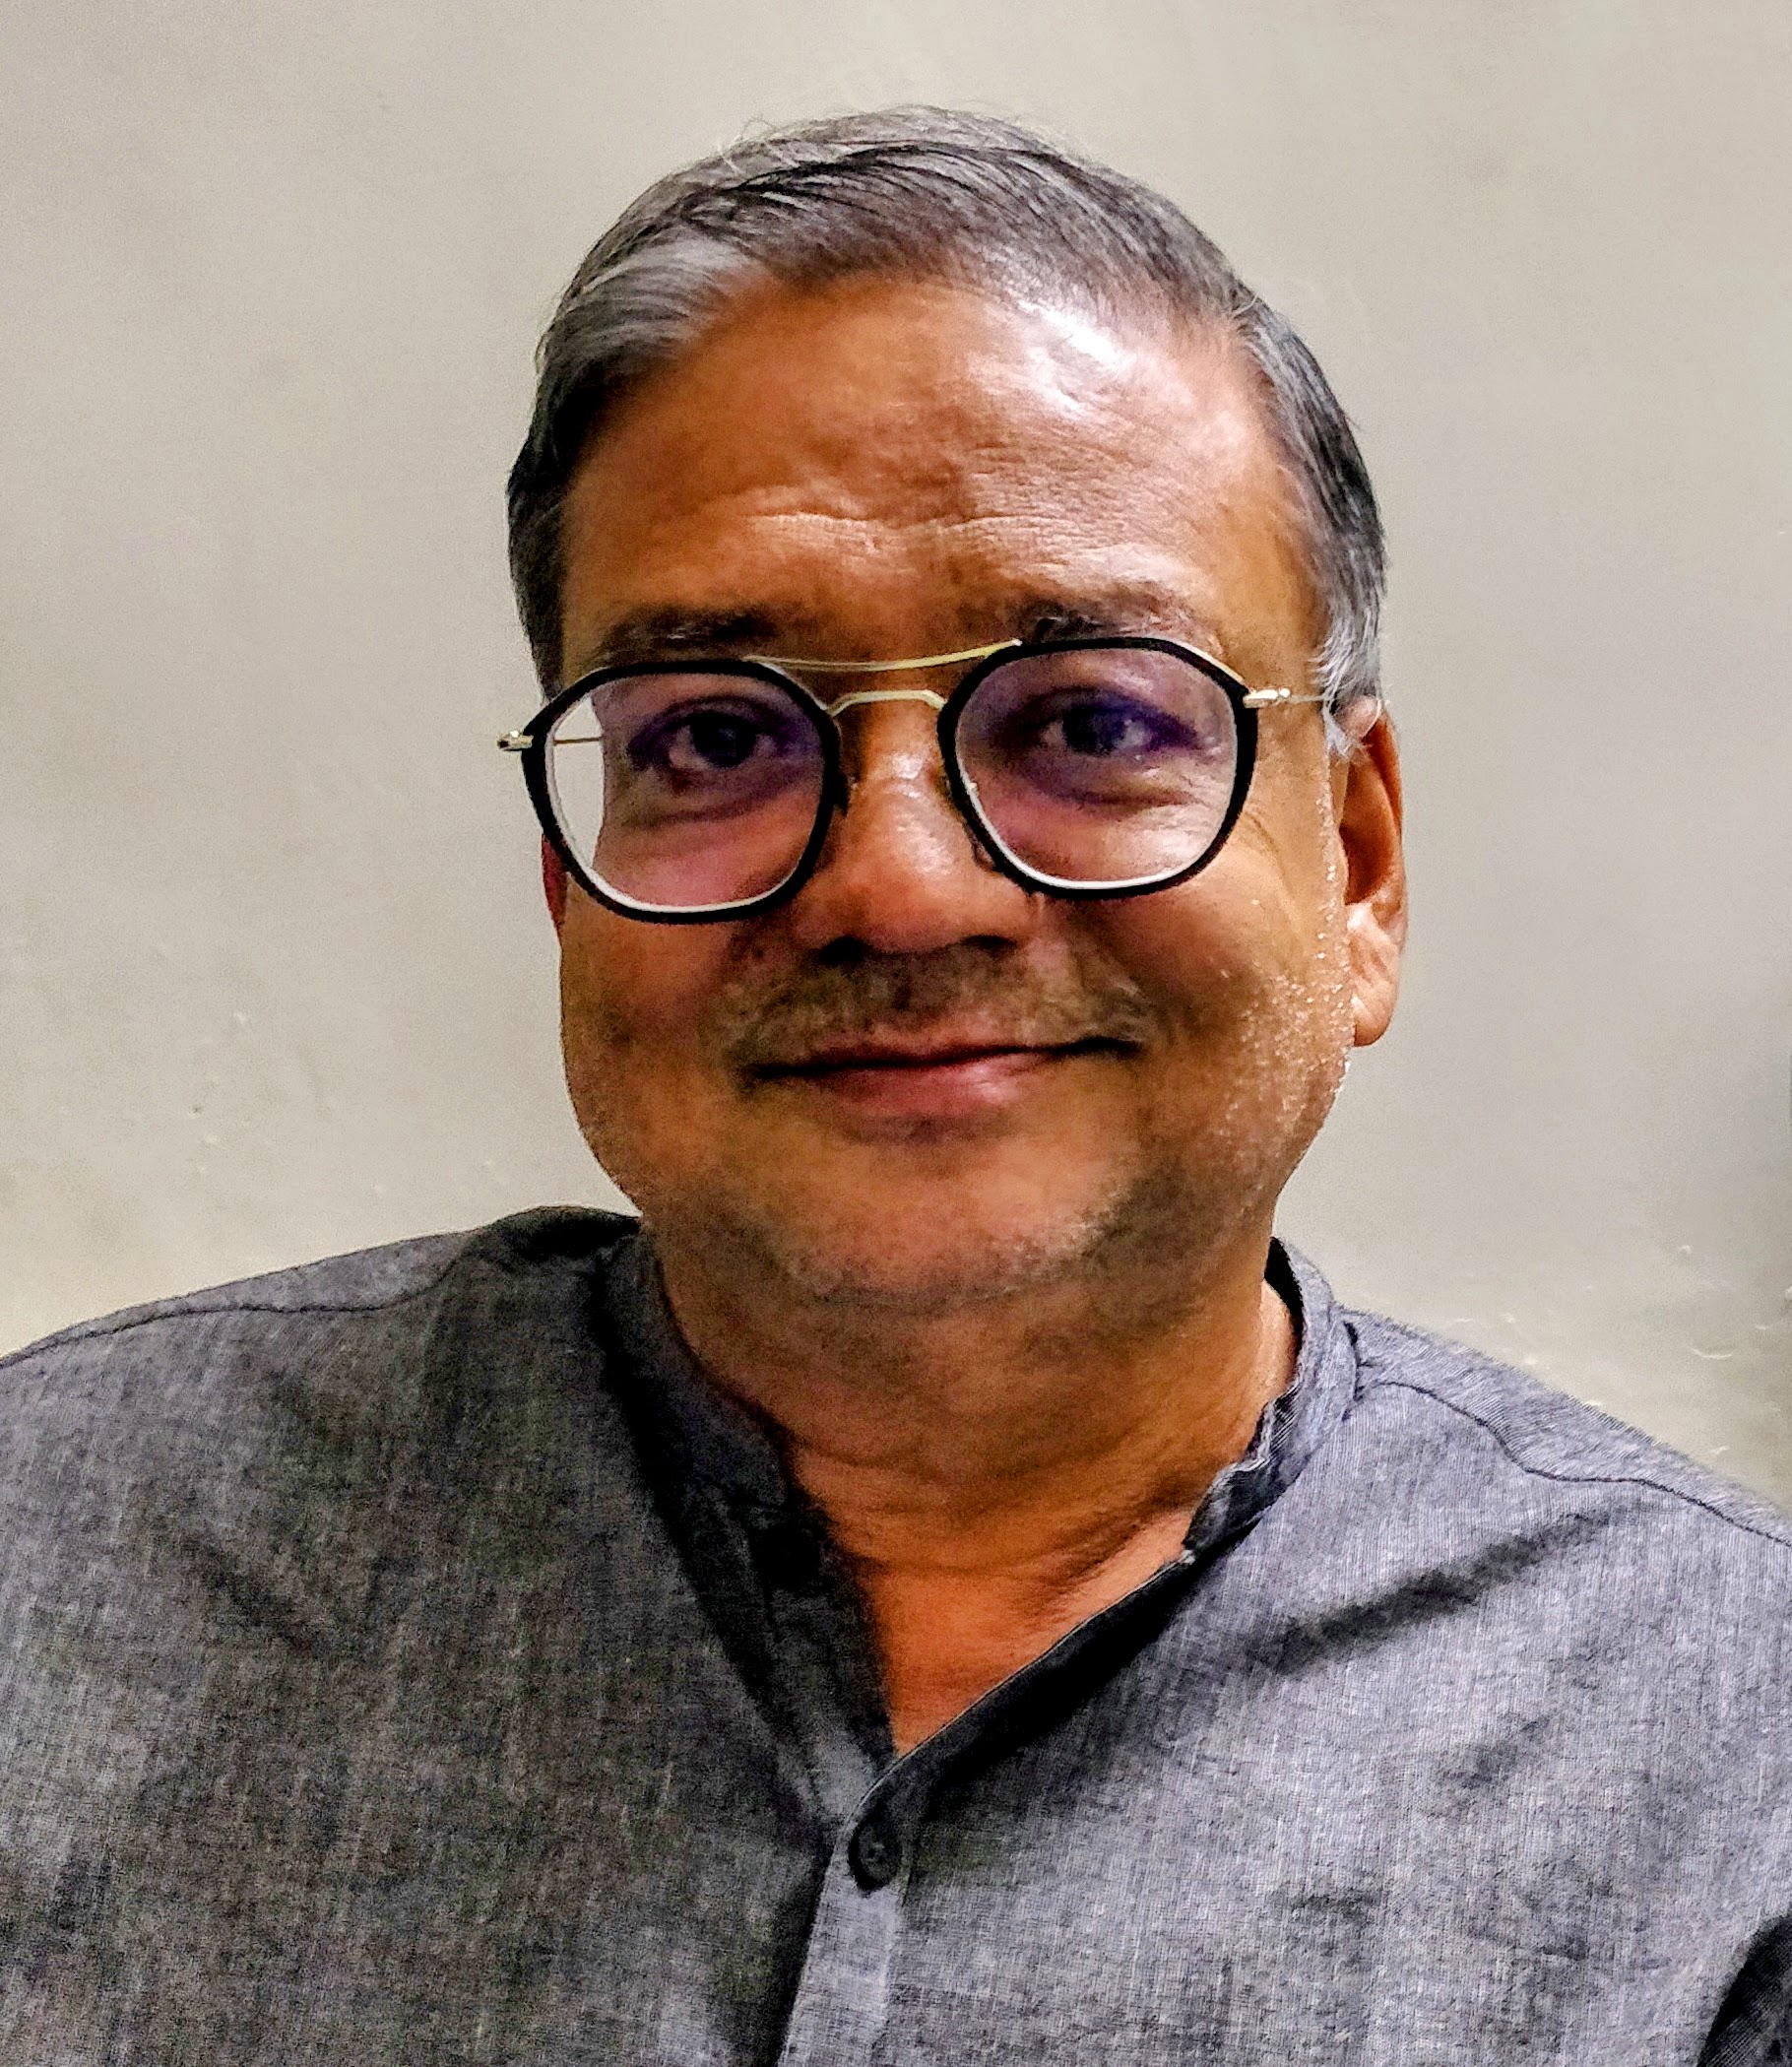
Late 1980s — founded

The Late Shree Mukesh Babulal Shah

The Late Shree Mukesh Babulal Shah

🇮🇳

General & Life Insurance
Health Insurance · The New India Assurance
Life Insurance · LIC

His story →

Today — continued

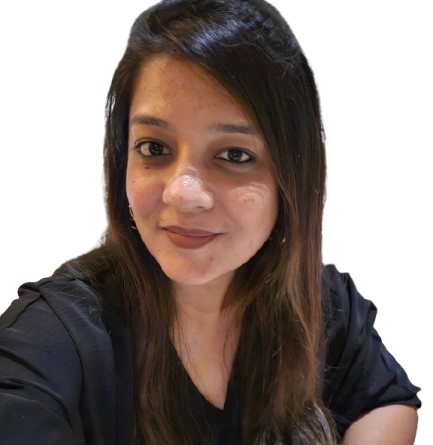
Priyanka Shah

Ms. Shah Priyanka

🇮🇳

General Insurance
Licensed The New India Assurance Agent
Licensed Care Insurance Agent

jmmukesh@gmail.com

Today — continued

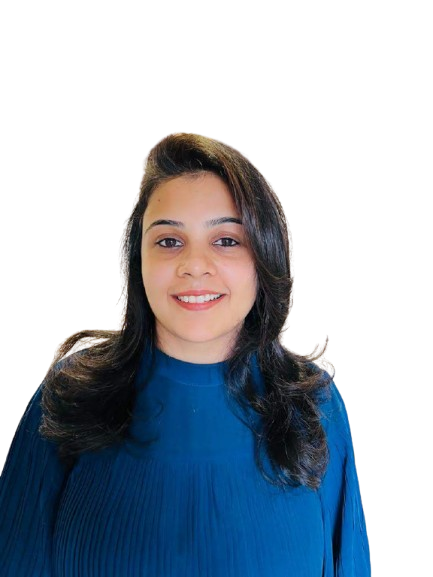
Heli Shah

Ms Heli Shah

🇨🇦

Licensed The New India Assurance Agent
Licensed Future Generali Insurance Agent

Support.jmcc@gmail.com

Today — continued

Shah

🇨🇦

Life Insurance & Wealth Investment
Licensed Tata AIA Insurance Agent
Licensed National Insurance Agent

Support.jmcc@gmail.com

★ In-house · indigenously developed by JMCC

Introducing the Saatvik Score™ for North American ETFs and shares.

India got its first values-based benchmark in June 2026, when BSE launched the Saatvik 100 — screening out alcohol, tobacco, gambling, narcotics, vulgar entertainment, meat and poultry, leather, pesticides and animal cruelty before it ever looked at a balance sheet. Nothing of the kind existed for the funds our families actually hold in Canada and the United States.

So we built it ourselves. The Saatvik Score™ is JMCC's own rating — our method, our screening list, our work — scoring any US or Canadian ETF or share out of 100 on what it owns and how it behaves. You will not find it anywhere else.

Ahimsa · 70 pointsWhat the fund actually owns, measured against nine families of excluded business. It carries most of the hundred, because it is most of the question.
Sanyam · 10 pointsRestraint: leveraged, inverse and option-income products are trading instruments, not holdings.
Sthirata · 13 pointsSteadiness — volatility, deepest fall, and how many months ended higher.
Paardarshita · 7 pointsTransparency: track record, liquidity, and whether holdings are disclosed at all.

77/ 100

Largely saatvik
  • Ahimsa 53.2 / 70
  • Sanyam 10 / 10
  • Sthirata 8.5 / 13
  • Paardarshita 5.3 / 7

An illustration of the format, not a rating of any particular fund. Run your own symbol to see the real one.

Conceptualised, designed and developed by

Mr. Sarthak M Shah Er.sarthak@outlook.com

Saatvik Score™ is an in-house rating developed independently by JMCC (JM Consultancy). ™ denotes an unregistered mark claimed by JMCC. Not affiliated with, endorsed by, or derived from the BSE Saatvik 100 index or BSE Index Services — that index rates Indian shares; this score is JMCC's own method for North American listings, and shares only the values tradition behind it. The score is JMCC's editorial opinion, general information only, and not investment advice.

NRI term plans · the one to read first

Your family is in India. Your cover should be too.

Indian term cover is a fraction of what the same sum assured costs in Canada, the US, the UK or the Gulf — and the claim is paid in rupees, in India, to the people who actually need it. You do not need to fly down to buy it.

01

Indian rates, from abroad

A rupee-denominated term plan is priced off Indian mortality tables, not your country of residence. For most NRIs that is the single biggest saving on the whole financial plan.

02

No trip to India needed

Tele-medicals and video underwriting are standard now. Passport, proof of residence, an income document — and we run the file for you from here.

03

The payout lands where it is needed

Parents, spouse, children in India get rupees into an Indian account, with no remittance to arrange at the worst possible moment.

04

Buy it while you are young

The premium is locked at the age you buy and never rises for the whole term. Every year you wait is a permanently more expensive policy.

Most asked for

Tata AIA · Term Insurance for NRIs

Pure protection. A large sum assured for a small premium, with nothing bundled in that you did not ask for.

  • Open to NRIs and OCI holders — bought and serviced entirely from where you live.
  • Cover to age 100 options, plus return-of-premium and limited-pay variants if you would rather finish paying early.
  • Riders worth attaching now — critical illness, accidental death, waiver of premium. They cost a fraction of the base premium.
  • Section 45 protection — after three years, a life policy cannot be questioned. Disclose everything and that clock works for you.
Pairs with it

Cover for the parents you left behind

The other half of an NRI file, and the half people forget: health cover for parents in India, arranged from abroad and serviced on the ground by us.

  • Family floater and senior-citizen health plans from The New India Assurance — the line of work my father started in.
  • A cancer lump-sum benefit alongside the regular policy rather than instead of it.
  • Someone in India who picks up. At claim time a policy is only as good as the person handling it, and we are in Ahmedabad.

The New India Assurance · The National Insurance

Eligibility, the sum assured on offer, the medicals required and the currency you may pay in are set by the insurer and by your country of residence. Insurance is a subject matter of solicitation — please read the sales brochure and policy wording before concluding a sale.

NRI investment plans · rupee growth

Earn abroad. Build the corpus in India.

If you are sending money home anyway, send it somewhere it compounds. Param Raksha is the plan NRI families ask us about most — market-linked funds and life, accident and health cover inside one policy, in rupees, back home.

  • Dual benefit. Life cover running alongside market-linked investment funds — several of the fund options carry 4- and 5-star Morningstar ratings.
  • Inbuilt protection. Accidental death, total and permanent disability, and terminal illness cover come built into the plan.
  • Wellness and OPD. Health Buddy / Vitality wellness programmes, outpatient cover that can extend to family members, and premium discounts for meeting healthy-habit targets.
  • Flexibility. Partial withdrawals once the five-year lock-in is done, and a choice of premium-paying terms.
  • The Rule of 72. Divide 72 by your return and you have the years to double. At 12 per cent that is six years — which is why starting this at 32 rather than 42 is worth more than any fund you pick.

Buying it from abroad. NRIs and OCI holders can take this on without a trip to India, subject to Tata AIA's country and medical rules. Before you commit to anything, we'll tell you exactly what's involved — passport type, proof of residence, the tele-medical or medical you'll need, and which account the premium can be paid from. Ask us about the tax treatment where you live before you commit.

Unit-linked funds carry investment risk: the value of your units can fall as well as rise, past fund performance is not a guide to future returns, and you carry that risk, not the insurer. Benefits, riders, eligibility, charges and the lock-in are as defined by Tata AIA in the policy wording — please read the sales brochure before concluding a sale.

Products we offer

Three things, done properly.

We don't sell everything. We place the covers we understand well enough to explain to you in plain language — and to service years after the paperwork.

Family & parents

Health insurance

Individual and family floater cover, including for parents. The line of work my father started in, and the one we know best.

The New India Assurance · The National Insurance

Rupee growth

Investment-linked plans

Plans that build a corpus alongside the cover — including options built for NRIs investing back into India.

Tata AIA Life Insurance

History · in memory

The Late Shree Mukesh Babulal Shah

Founder · 1994

He began with The New India Assurance Co., working from Mill Officers Colony. Families called him first, before the hospital, before the bank, before anyone else.

He isn't here to take those calls now. The practice still answers them.

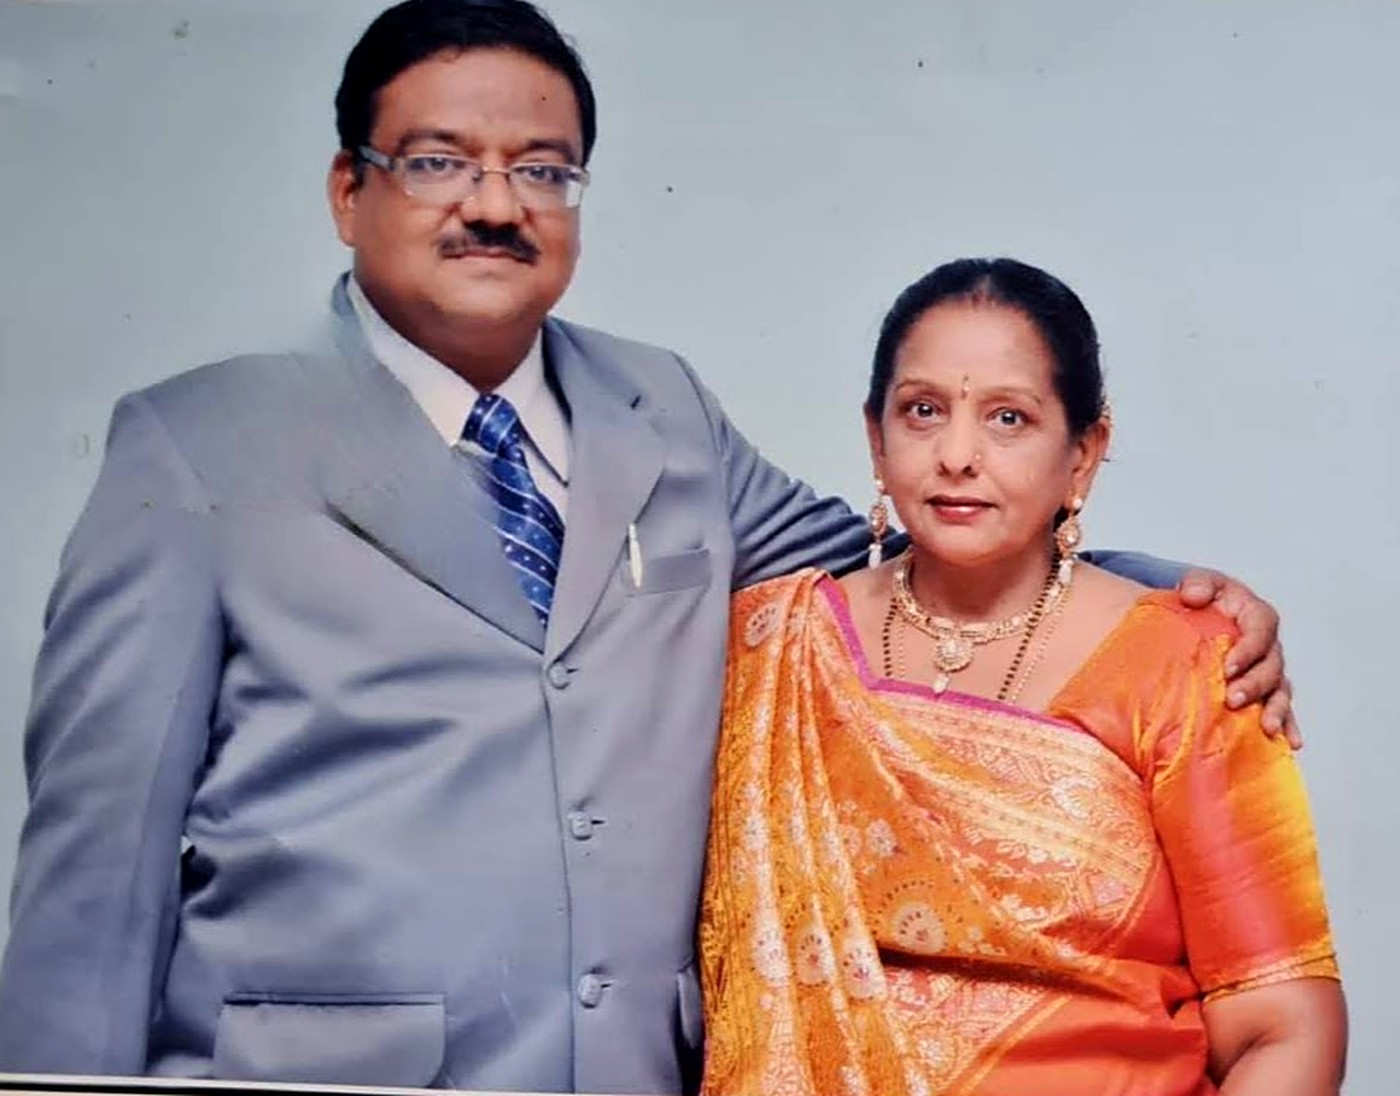
Mukesh Babulal Shah with his wife

My father and my mother

My late mother was the stronger hand for my father; she had an outstanding, welcoming nature and always made anyone who came to our home feel at ease. My father mostly worked and operated from our home at Manish Society, Ahmedabad 380013.

  1. The beginning

    The New India Assurance Co.

    A career spent on general and life insurance, out of Mill Officers Colony — health cover with New India, life cover with LIC.

  2. 2004

    A VRS, and a practice of his own

    He took the Voluntary Retirement Scheme and started JM Consultancy, working mostly from our home at Manish Society, Ahmedabad.

  3. The way he worked

    One family at a time

    Almost every client came through a friend, or a friend of a friend. Nobody was ever sold something they could not explain back to him.

  4. Today

    The same desk, two countries

    Priyanka and Heli on general and health, Sarthak on life and wealth — India and Canada, serving Indian families wherever they have moved.

Worth knowing · nothing to buy here

The questions people feel silly asking.

Nobody is born knowing what a rider is, or why one insurer's claim ratio looks better than another's. Here is the plain version of what gets asked most often across our desk — and a rough sum to start you off.

How much life cover, roughly?

The usual rule of thumb is ten to fifteen times your annual income, plus whatever you still owe.

A sensible range to aim at

₹1.2 crore₹1.8 crore

A starting point, not a quote — your age, your health and how many people lean on that income all move it. Send us your details and we'll size it properly.

What is the sum assured?

The amount the insurer pays your nominee if the claim is made. Premium out, sum assured in — that is the whole equation on a term plan.

On a plan that also invests, keep the two numbers apart in your head: the sum assured is the protection, the fund value is the savings. They are not the same money and a good plan tells you both.

What is a rider, and do I need one?

A rider is a small add-on bolted to the main policy — critical illness, accidental death, or a waiver that keeps the policy alive if you can no longer pay the premium.

They cost a fraction of the base premium and are easiest to attach when you first buy. Riders are cheap; regret is not.

Can I buy an Indian policy while living abroad?

Yes. NRIs and OCI holders buy Indian term and unit-linked plans routinely, without flying down — tele-medicals, video verification and digital documents are standard, subject to the insurer's country rules.

What you will need: passport and visa or OCI card, proof of overseas address, an income document, and an NRE or NRO account to pay from. Tax treatment depends on where you are resident, so ask us before you commit.

What does a claim settlement ratio really tell you?

It is claims paid divided by claims received, over a year. Useful, but one ratio never tells the whole story.

It counts every policy the insurer wrote, not just the kind you are buying, and counting by number of claims flatters an insurer whose claims are mostly small. Look at the amount settled too, and at more than one year.

What is the free look period?

A window after the policy document reaches you in which you can read it properly and return it for a refund, less a small charge, if it is not what you were told it was.

Fifteen days is the floor, and thirty is now usual on life policies. Your policy schedule states the exact window — that is the number that counts, so read the document the week it arrives rather than filing it.

What happens if I miss a premium?

You get a grace period — usually thirty days on yearly, half-yearly and quarterly premiums, and fifteen on monthly. Cover continues through it.

Miss the grace period and the policy lapses, and reviving it can mean fresh paperwork or fresh medicals. A grace period is not a holiday: set a standing instruction and stop relying on memory.

Why does disclosure matter so much?

Almost every rejected-claim story starts with something that was not written on the form — a health condition, a habit, an existing policy, real income.

The law is on your side once time has passed: under Section 45 of the Insurance Act, a life policy cannot be questioned after three years from when it started or was last revived, on any ground at all. Before three years it can be, if something was misstated. Disclosing everything is what turns that clock into your protection instead of the insurer's.

Health cover and life cover are not the same thing

Health insurance pays hospitals while you are alive. Life insurance pays your family when you are not. Two different risks, two different products, and one does not stand in for the other.

A term plan will not pay a hospital bill, and the largest family floater will not replace a salary.

The Rule of 72 — the fastest maths in finance

Divide 72 by an annual return and you get the years it takes to double your money. At 12 per cent: 72 ÷ 12 = six years. At 8 per cent, nine.

It works in reverse on costs, which is the half nobody mentions. And if someone quotes you a return without saying over how long, they have told you nothing — ask for the CAGR.

Still on your mind after all that? Ask us — we answer questions from people who never end up buying anything, and that is fine.

Join the family

Become part of the JMCC family.

Almost everyone here came through a friend, or a friend of a friend. Leave your details and we'll call you — no obligation, and no pressure to buy anything on the first call.

$100 Amazon gift card on joining.

Sign up, then sit down with us for your complimentary financial-planning session — a proper look at cover, goals and gaps before any product talk. We send the $100 Amazon gift card after that session. One per household, first-time sign-ups only, and it is never conditional on buying a policy or adjusted against a premium.

Sent.

Thank you for signing up. Check your email for a confirmation — we'll follow up with you shortly on WhatsApp.

Your $100 Amazon gift card

We'll set up your complimentary planning session on WhatsApp, and the card follows straight after it.

We place cover with

Tata AIA Life Insurance
The New India Assurance
The National Insurance
Sign up — join the JMCC familyJoin & get $100 Amazon card